Nvidia Corp. (NASDAQ:NVDA) has returned as Morgan Stanley’s preferred semiconductor stock, with analysts pointing to valuation, stronger earnings expectations, and the company’s position in an evolving AI infrastructure market.
Analyst Joseph Moore said discussions with CEO Jensen Huang, CFO Colette Kress, and investor relations chief Toshiya Hari reinforced the bank’s confidence in Nvidia’s market position, Investing.com reported.
“We certainly see Nvidia as well positioned, with a very undemanding valuation,” Moore wrote.
Morgan Stanley said the principal constraints on AI infrastructure are moving away from chip production and toward constructing and financing additional data centers, a shift that could support Nvidia’s extensive cloud-partner network. NVIDIA identifies 80 cloud partners, including 55 outside the U.S.
Moore pointed out that Nvidia’s customer base is much broader than investors tend to focus on. Most investor conversations center on the biggest hyperscalers and frontier model companies, but roughly half of Nvidia’s business comes from other customers, including smaller AI model companies, neoclouds, sovereign entities, server makers (ODMs and OEMs), and enterprises. He suggested that this half is probably growing faster.
He highlighted Nvidia’s strategy of raising revenue per gigawatt of capacity, with the 2028 Feynman architecture expected to push that figure from $40 billion to well over $50 billion.
Furthermore, Moore stated that the growth of AI agents could lift CPU demand while driving significantly greater spending on graphics processing units, or GPUs.
$150 Billion Buyback Wins Praise
The move follows Nvidia’s announcement of a record $150 billion stock buyback earlier this week, a move that drew favorable reactions from market experts. Gary Black, managing partner at The Future Fund, said Nvidia’s stock buyback lifts its total buying power to $235 billion.
He estimates that, at a $5.6 trillion market cap, the buyback would shrink the share count by about 4.2% over the next 16 months. Net of interest income lost on the cash used to fund it, he sees a potential 1.6% boost to 2028 adjusted EPS.
Growing AI Spending Scrutiny
Nvidia has profited hugely from the AI boom, but investors are starting to ask how long hyperscalers can keep spending heavily before demanding clearer returns. Sam Rines, Macro Strategist at WisdomTree, says that the test has already begun, telling Benzinga that the market tolerates big capex from companies that can show returns, but not from those that can’t explain them.
Meanwhile, investor Michael Burry compared Nvidia’s defense of its GPU depreciation schedules to a 1960s market bubble. Citing Adam Smith’s The Money Game, Burry argued that investors’ optimism about Nvidia’s AI infrastructure, valuations and future demand echoes past speculative bubbles, suggesting that despite technological changes, investor psychology and speculative narratives remain largely unchanged.
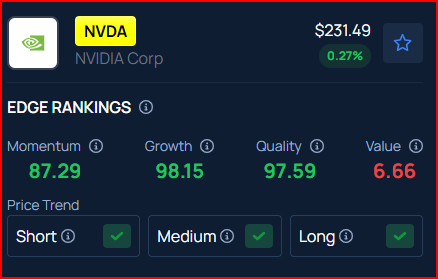
Benzinga’s Edge Rankings place Nvidia in the 97th percentile for quality and the 98th percentile for growth, reflecting its strong performance in both areas. Benzinga’s screener allows you to compare NVDA’s performance with its peers.
Price Action: On a year-to-date basis, Nvidia stock surged about 26.62%, as per Benzinga Pro. On Friday, the stock was trading 2.46% higher at $236.53.
Disclaimer: This content was partially produced with the help of AI tools and was reviewed and published by Benzinga editors.
Image via Shutterstock
Recent Comments